Colorado Hail Season 2026: How to File a Roof Insurance Claim
Colorado experiences more hail damage per year than almost anywhere in the United States. If a storm has moved through your neighborhood recently and you're not sure whether your roof was affected — or you know it was and aren't sure what to do next — this guide walks through the full process, step by step.
The claims process is more straightforward than many homeowners expect, but the outcome depends heavily on how well the damage is documented before an adjuster visits.
Step 1 — Do a Preliminary Check From the Ground
Immediately after a storm, check what you can safely see without going on the roof:
- Gutters and downspouts: dents or dings in aluminum gutters are one of the clearest indicators of hail impact size — they're at eye level and show impact marks clearly.
- Window screens and AC unit fins: soft metal surfaces like screen frames and AC condensers show hail impact even from small stones that may not have penetrated shingles.
- Siding: look for circular impact marks, dents, or cracking, particularly on south and west elevations.
- Window sills and wooden trim: soft wood surfaces may show bruising or impact marks.
If any of these surfaces show damage, you almost certainly have roof damage too. Call a
licensed roofing contractor for a professional roof inspection before contacting your insurance carrier — you want an independent damage assessment first.
Step 2 — Get a Professional Roof Inspection Before Filing
This step is the one most homeowners skip, and it costs them. Filing a claim before having the roof professionally inspected means your adjuster's assessment is the only one on record. If the adjuster underestimates the damage — which happens — you have no independent documentation to reference.
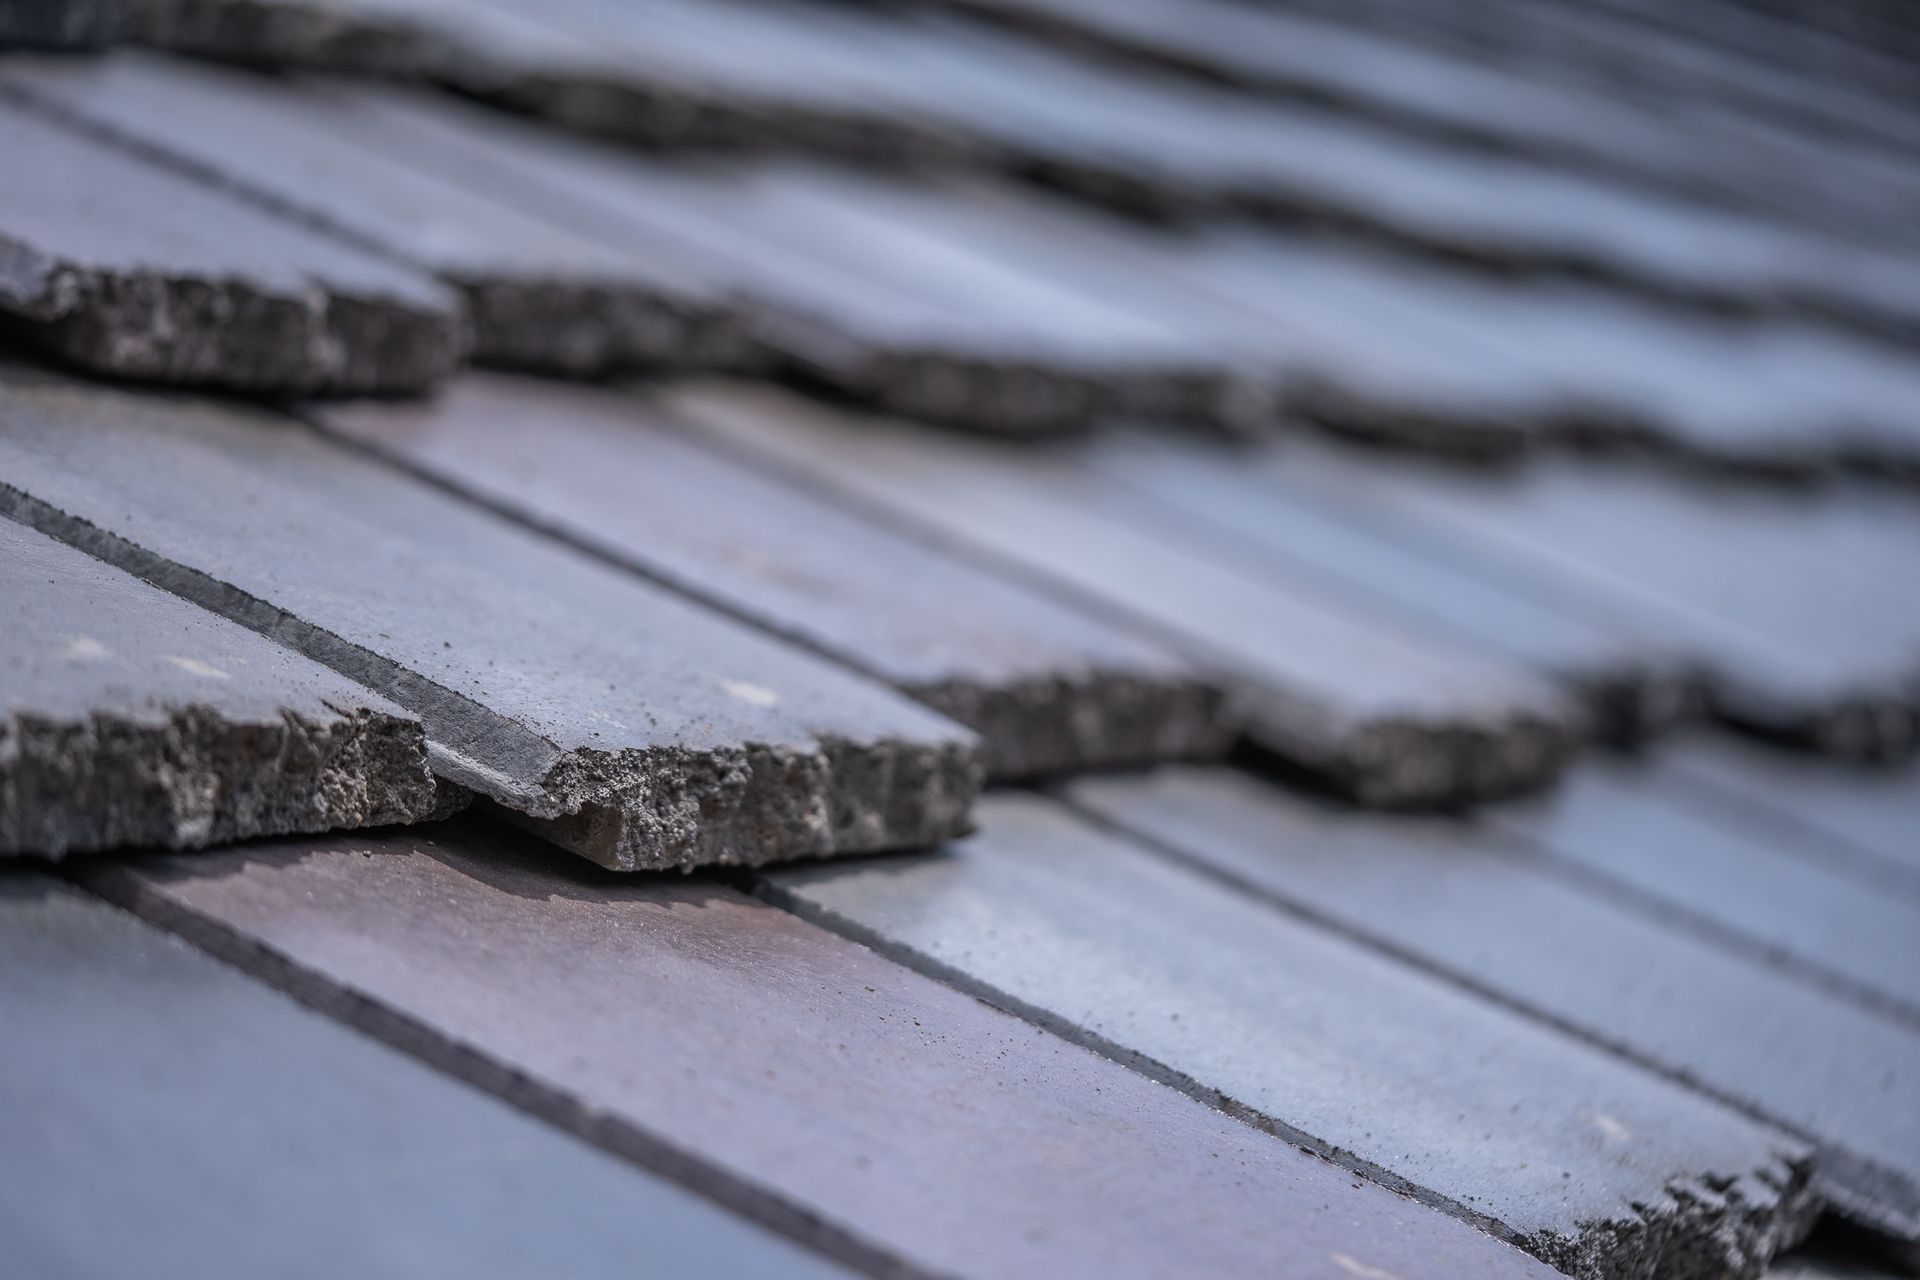
A qualified roofing contractor will inspect the field of the roof, ridge, valleys, flashings, pipe boots, gutters, and any skylights or ventilation components. They'll document hail impact patterns (size, density, and distribution across slopes), granule loss, denting to metal components, and any secondary damage to fascia, soffits, or siding.
This documentation — photos, written assessments, and measurements — is what you bring to your adjuster meeting. If you're in Aurora, our
Aurora shingle roofing team provides free post-storm inspections.
Step 3 — Contact Your Insurance Carrier and File the Claim
After you have professional documentation in hand, call your homeowners insurance carrier and report the damage. Most carriers have a 24-hour claims line. Have the following ready when you call:
- Your policy number and the name of your agent or carrier
- The approximate date of the storm (weather records are available online — hail reports are filed by county)
- A brief description of what was damaged
- The roofing contractor's written inspection report and photos, if you have them
The carrier will assign a claims adjuster and schedule an inspection. This typically takes one to two weeks in Colorado after a major storm event — longer during peak hail season when adjusters are handling high volumes.
Step 4 — The Adjuster Visit
You have the right to have your roofing contractor present when the adjuster inspects the roof. This is important — a contractor on-site can point out damage the adjuster might otherwise miss, ask clarifying questions about the scope assessment, and provide additional documentation if the adjuster's findings differ from the initial inspection.
If the adjuster's estimate is significantly lower than your contractor's assessment, you can request a supplemental claim or a second adjuster review. Disagreements between contractor scope and adjuster scope are common and are a normal part of the claims process.
Step 5 — Understand Your Policy Before Approving the Scope
Before work begins, confirm the following from your policy:
- Replacement Cost Value (RCV) vs Actual Cash Value (ACV): RCV pays the full cost of replacing the damaged material; ACV deducts for depreciation. Most standard homeowners’ policies are RCV for roofing, but this varies.
- Your deductible: Colorado has seen a rise in percentage-based hail deductibles (e.g. 1–2% of home value rather than a flat $1,000 or $2,500). Know your deductible before the claim is finalized.
- Extended Replacement Cost coverage: if your home is older or construction costs have risen significantly, your policy limit may not cover the full replacement cost. Extended coverage bridges that gap.
Need Help With a Hail Damage Claim in Colorado?
Formula Roofing & Remodeling assists Colorado homeowners through the full claims process — free inspection, damage documentation, adjuster meetings, and project completion. Visit our roof insurance claims page for full details or check our hail damage FAQ for common questions. Call (303) 600-8696 to schedule a free post-storm inspection.